 by
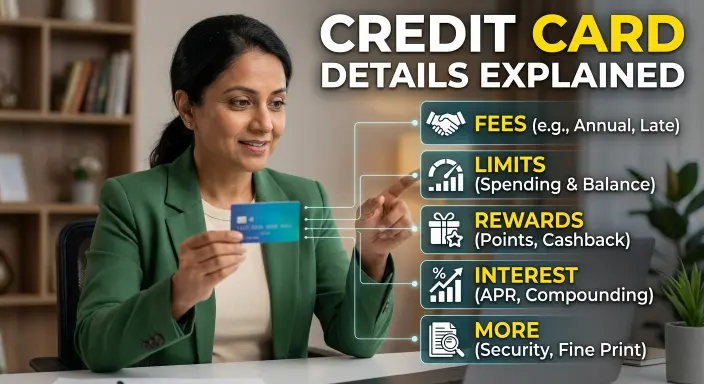
Credit cards can make everyday spending easier, but understanding how they work is just as important as knowing how to use them. A credit card comes with several features, including a credit limit, interest rate, fees, rewards, payment due date, and billing cycle. Each feature can affect the cost and usefulness of your card.
Many people focus only on the available credit shown in their banking app. However, there is much more information that deserves attention. Understanding your credit card details can help you make better spending decisions and avoid unnecessary costs.
In this guide, FinanceTrack America explains the most important credit card features in simple language, including fees, limits, rewards, interest, payments, and other common terms.
What Is a Credit Card?
A credit card is a payment tool that allows you to borrow money from a card issuer to make purchases. Instead of taking money directly from your bank account when you make a purchase, the card issuer generally pays the merchant and adds the transaction to your credit card account.
You then repay the amount according to the terms of your card agreement.
Credit cards can be useful for everyday purchases, emergencies, rewards, and building a credit history. However, they can also become expensive when balances are carried and interest or fees are charged.
Important Credit Card Details at a Glance
Before using a credit card, it helps to understand its major features.
| Credit Card Feature | Simple Meaning | Why It Matters |
|---|---|---|
| Credit Limit | Maximum amount of credit available | Determines your overall borrowing capacity |
| Available Credit | Credit currently available to use | Shows how much room remains on your account |
| APR | Annual percentage rate | Helps determine interest costs when carrying a balance |
| Annual Fee | Yearly charge for the card | Adds to the overall cost of having the card |
| Minimum Payment | Smallest required payment | Helps keep your account current when paid on time |
| Statement Balance | Amount shown on your billing statement | Important when deciding how much to pay |
| Payment Due Date | Date payment is due | Missing it can result in consequences such as late fees |
| Rewards | Points, miles, or cash back | Can provide value on eligible purchases |
| Foreign Transaction Fee | Fee that may apply to certain foreign transactions | Important for international spending |
| Cash Advance Fee | Fee associated with certain cash withdrawals | Can make cash advances expensive |
Understanding Your Credit Limit
Your credit limit is the maximum amount of credit your issuer has made available to you under your account terms.
For example, suppose your credit card has a $5,000 credit limit. This does not mean you should automatically spend $5,000 every month. It simply represents the amount of credit available under the account’s terms.
Your credit limit can affect how much available credit remains after purchases are posted.
Credit limits may vary between cardholders and can change over time depending on the issuer’s policies and account circumstances.
What Is Available Credit?
Available credit is the amount of your credit line that remains available for use.
For example, if your credit limit is $5,000 and your account has $1,000 in posted purchases, your available credit may be approximately $4,000, although pending transactions and other account activity can affect the exact figure.
Checking available credit before making a large purchase can help you understand how much credit remains.
What Is Credit Card APR?
APR stands for Annual Percentage Rate. It is an important number because it helps explain the annualized cost of borrowing under the card’s terms.
A credit card may have different APRs for different types of transactions. For example, purchase APR, balance transfer APR, and cash advance APR may not be the same.
If you normally pay your statement balance in full and on time, you may be able to avoid interest on purchases when the card provides a grace period and you meet its requirements.
However, carrying a balance can result in interest charges.
How Credit Card Interest Works
Credit card interest is one of the most important costs to understand.
If you carry a balance from one billing period to another, interest may be charged according to the terms of your account. The exact calculation can depend on the card’s APR, average daily balance, transaction type, and other account terms.
For example, imagine you carry a $1,000 balance and your applicable APR is relatively high. Keeping that balance for an extended period can make the purchase more expensive because interest continues to add to what you owe.
This is why understanding the interest rate and paying balances responsibly is important.
What Is an Annual Fee?
An annual fee is a yearly charge for having certain credit cards.
Some cards have no annual fee, while others charge a fee in exchange for rewards, travel benefits, insurance-related features, discounts, or other perks.
An annual fee does not automatically mean a card is bad. The important question is whether the benefits you actually use provide enough value to justify the cost.
For example, a card with a $95 annual fee may still make sense for someone who receives benefits worth more than that amount.
Understanding Credit Card Rewards
Rewards are another major feature of many credit cards.
Depending on the card, rewards may come in the form of cash back, points, miles, discounts, or other benefits.
However, reward programs can have different rules. Some cards offer higher rewards for specific categories, while others provide a flat reward rate on eligible purchases.
Before choosing a card because of its rewards, check:
- How rewards are earned
- Which purchases qualify
- Whether rewards expire
- How rewards can be redeemed
- Whether there are redemption restrictions
- Whether an annual fee applies
The best rewards card is not necessarily the one with the highest advertised reward rate. It should fit your normal spending habits.
Credit Card Fees You Should Know
Credit cards can have several different types of fees.
Common examples include annual fees, foreign transaction fees, balance transfer fees, cash advance fees, late payment fees, and returned payment fees.
Not every card charges every fee.
Always read the fee information provided by your card issuer. Understanding the fee structure before using the card can help you avoid unexpected expenses.
What Is the Minimum Payment?
The minimum payment is the smallest amount you generally need to pay by the due date according to your card’s terms.
Paying the minimum can help keep your account from becoming past due, but it does not necessarily mean you are avoiding interest.
If you carry a balance, paying only the minimum can take much longer to repay the debt and may increase the total interest you pay.
When financially possible, paying the statement balance in full can be a more cost-effective approach.
Statement Balance vs. Current Balance
These terms can sometimes cause confusion.
Your statement balance is generally the amount shown on your most recent billing statement for that billing cycle.
Your current balance can change as new purchases, payments, credits, and other transactions are posted after the statement was generated.
For this reason, these two amounts may not always be identical.
Reviewing both can help you understand your account more clearly.
Why the Payment Due Date Matters
The payment due date tells you when your required payment must be received according to your card issuer’s terms.
Missing a payment can result in late fees and may have other consequences depending on the account and circumstances.
A simple way to stay organized is to use automatic payments, calendar reminders, or notifications from your card issuer.
Even if you use automatic payments, regularly reviewing your account is still important.
What Are Foreign Transaction Fees?
A foreign transaction fee is a fee that some credit cards may charge for certain transactions processed outside the card’s home country or involving foreign currencies.
This feature is particularly important for people who travel internationally or regularly purchase products and services from businesses outside their country.
Some cards do not charge foreign transaction fees, but you should always check the specific terms of your card rather than assuming.
What Is a Cash Advance?
A cash advance allows a cardholder to access cash using a credit card under the issuer’s cash advance terms.
Cash advances can be expensive because they may involve a separate fee and a different interest rate. Interest may also begin accumulating immediately rather than benefiting from the same purchase grace period.
Because of these costs, it is important to understand the terms before using a credit card for cash.
Check Your Credit Card Details Regularly
You do not need to wait for a problem before reviewing your credit card account.
Once or twice each month, check your transactions, current balance, available credit, payment due date, minimum payment, statement balance, fees, interest charges, and rewards.
Also look for transactions that you do not recognize. If something appears suspicious, contact your card issuer through an official channel.
Never provide your password, PIN, security code, or one-time verification code to someone who unexpectedly asks for it.
How to Choose a Credit Card Based on Its Features
When comparing credit cards, avoid looking at just one feature.
Consider the complete picture. A card with excellent rewards may have an annual fee. Another card may have fewer rewards but no annual fee. A card with a low introductory rate may later have a different standard APR.
Think about your spending habits and ask:
- Will I pay my balance in full?
- Do I frequently travel?
- Will I use the rewards?
- Is there an annual fee?
- What fees could apply to my normal transactions?
- What APR applies after any introductory period?
- Are the benefits useful to me?
These questions can make comparing cards much easier.
Final Thoughts
Understanding your credit card details can help you become a more informed cardholder. Credit limits tell you how much credit is available, APR helps explain potential interest costs, fees can increase the cost of using the card, and rewards can provide value when used appropriately.
Your payment due date and minimum payment are also important because they help you manage your account and avoid missed payments.
Most importantly, never choose a credit card based on one advertised feature alone. Look at the complete terms, including fees, interest rates, rewards, benefits, and payment requirements.
By checking your credit card account regularly and understanding what each number means, you can use your card more confidently and make decisions that fit your financial goals.
FinanceTrack America provides educational information about credit cards, banking, and personal finance to help readers better understand everyday financial decisions.