 by
When choosing a credit card, one of the first things people often look at is the rewards rate. However, there is another important detail that should never be ignored: the annual fee.
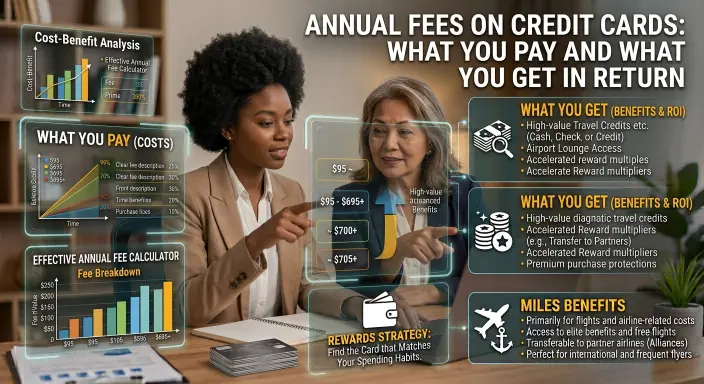
An annual fee is a charge that some credit card issuers apply for keeping a particular card. Some cards have no annual fee, while others charge a yearly amount in exchange for rewards, travel benefits, statement credits, insurance-related features, or other perks.
Paying an annual fee is not necessarily a bad thing. The real question is whether the benefits you actually use provide enough value to justify the cost.
In this guide, FinanceTrack America explains how credit card annual fees work, what you may receive in return, and how to decide whether a fee-based card makes sense for you.
What Is a Credit Card Annual Fee?
An annual fee is a recurring charge for having certain credit cards.
For example, a card may charge an annual fee of $95 or $550, depending on the product and benefits offered. The fee is generally separate from interest charges and other account fees.
Some cards do not charge an annual fee at all. Others charge a fee because they offer additional rewards or benefits.
The amount and timing of the annual fee depend on the card’s terms.
Why Do Credit Cards Charge Annual Fees?
Credit card companies may charge annual fees on cards that provide enhanced rewards or additional benefits.
A card with an annual fee may offer features such as:
- Higher rewards rates
- Travel rewards
- Travel-related credits
- Airport lounge access
- Purchase protections
- Hotel or airline benefits
- Exclusive discounts
- Flexible rewards
- Other premium services
However, the presence of these benefits does not automatically make the card worthwhile.
You need to consider whether you will actually use them.
Annual Fee vs. No Annual Fee
The basic difference is easy to understand.
| Card Type | Annual Fee | Typical Focus | Who May Consider It |
|---|---|---|---|
| No-Fee Card | $0 | Basic spending and simple rewards | People wanting low ongoing costs |
| Low-Fee Rewards Card | Usually modest | Cash back or points | Regular rewards users |
| Travel Rewards Card | Varies | Miles and travel benefits | Frequent travelers |
| Premium Card | Often higher | Extensive travel and lifestyle benefits | People who can use multiple benefits |
| Business Card | Varies | Business spending and rewards | Eligible business users |
These are general categories. Actual fees and benefits vary by card.
What Do You Get in Return?
The value of an annual-fee card depends on its benefits.
For example, a card may offer a higher cash-back rate than a no-fee card. Another may provide travel credits or other perks that can reduce expenses.
Suppose a card charges a $95 annual fee but provides rewards and benefits that you realistically value at $200 per year. In that simplified example, the card could potentially provide $105 more value than the fee.
However, you should use realistic values rather than advertised maximums.
If a benefit is only useful when you spend more money or use a service you do not need, its practical value to you may be much lower.
Calculate Your Real Annual Value
One of the easiest ways to evaluate an annual fee is to calculate the value you expect to receive during a normal year.
Consider:
Annual rewards + useful benefits − annual fee = potential net value
For example:
- Annual rewards: $150
- Benefits you actually use: $100
- Annual fee: $95
Potential net value:
$150 + $100 − $95 = $155
This is only a simplified example. Your actual value depends on the card’s terms, your spending, and whether you can use the benefits.
Don’t Count Benefits You Won’t Use
This is one of the most important points when comparing annual-fee cards.
A card might advertise a large collection of benefits, but that does not mean you will personally receive the full value.
For example, imagine a card provides a travel credit that requires you to make eligible purchases. If you do not normally make those purchases, the full advertised credit may not be useful to you.
The same applies to airport lounge access, hotel credits, shopping benefits, and other perks.
Focus on benefits that naturally fit your lifestyle.
Rewards Can Help Offset an Annual Fee
Rewards are one of the most common ways cardholders may recover the cost of an annual fee.
Suppose a card has a $95 annual fee and provides higher rewards than a no-fee alternative.
You could compare the estimated annual rewards from both cards.
For example:
Card A: $95 annual fee and $300 estimated yearly rewards
Card B: No annual fee and $180 estimated yearly rewards
In this simplified scenario, Card A could provide $205 in rewards after subtracting the annual fee, while Card B provides $180.
The difference would be $25.
This shows why you should compare the net value, rather than simply looking at the rewards rate.
Check When the Annual Fee Is Charged
Annual fees can be charged according to the issuer’s account terms.
Some cards may charge the fee when the account is opened and then annually. Others may charge it on a particular statement.
Read your card agreement to understand when the fee applies.
You should also check whether the fee changes after the first year. Some promotional offers may waive or reduce the first-year fee while applying the standard annual fee afterward.
First-Year Fee Waivers
Some credit card offers may include a promotional period where the annual fee is waived for the first year.
This can make a card look less expensive initially.
However, before applying, check what happens after the promotional period ends.
If the card charges a significant annual fee starting in the second year, calculate whether the ongoing benefits will still justify the cost.
Annual Fees Are Different From Interest
An annual fee and interest are two completely different costs.
The annual fee is a charge associated with maintaining the card according to its terms.
Interest is generally the cost of carrying a balance when interest applies.
For example, a card could have:
- $95 annual fee
- Variable purchase APR
- Foreign transaction fee
- Cash advance fee
These costs are separate.
A card with a $0 annual fee can still become expensive if you carry a balance and incur significant interest.
Likewise, an annual-fee card can potentially be valuable if its benefits outweigh the fee and you manage the balance responsibly.
Consider Your Spending Habits
Your spending habits are an important part of the decision.
Ask yourself:
- How much do I normally spend each month?
- Do I travel frequently?
- Will I use the card’s rewards categories?
- Can I use its credits naturally?
- Will I use the additional benefits?
- Am I comfortable paying the annual fee every year?
The answers can help you determine whether an annual-fee card fits your needs.
When a No-Annual-Fee Card May Be Better
A no-annual-fee card may be a better choice if you want a simple credit card with minimal ongoing costs.
It can also make sense if you do not spend enough to generate meaningful rewards from a fee-based card or if you would not use the premium benefits.
For example, someone who wants a straightforward card for occasional purchases may prefer a no-fee option over a premium rewards card.
Again, the best choice depends on the individual’s circumstances.
When an Annual-Fee Card May Make Sense
An annual-fee card may make sense when the benefits provide more value than the cost.
This could happen when you:
- Spend regularly in high-reward categories
- Travel frequently
- Can use available travel credits
- Make use of premium benefits
- Earn enough rewards to offset the fee
- Value the card’s additional protections or services
The key is actual usage, not the number of benefits listed in the advertisement.
What to Check Before Applying
Before choosing an annual-fee credit card, review the complete terms.
Check the annual fee, APR, rewards structure, welcome bonus, benefit requirements, redemption rules, foreign transaction fees, balance transfer fees, cash advance fees, and other charges.
Also look at the ongoing annual fee after any introductory offer ends.
Do not make your decision based solely on the welcome bonus.
A large first-year bonus may be attractive, but the card needs to provide value after the promotion ends if you plan to keep it long term.
Final Thoughts
An annual fee is not automatically a sign that a credit card is expensive or unsuitable. Some annual-fee cards can provide valuable rewards and benefits that exceed the yearly cost.
However, the benefits only have value if you can realistically use them.
Before applying, compare the annual fee with the rewards and benefits you expect to receive. Consider your normal spending habits, travel needs, payment behavior, and long-term use of the card.
A simple no-annual-fee card may be the better choice for someone who wants low ongoing costs, while an annual-fee card may make sense for someone who regularly uses its additional rewards and benefits.
The most important thing is to calculate your personal value, not the maximum value advertised by the card issuer.
Always review the current terms and conditions provided by the card issuer because annual fees, rewards, benefits, and promotional offers can change.
FinanceTrack America provides educational information about credit cards, banking, rewards, and personal finance to help readers better understand financial products and make informed decisions.