 by
Choosing a credit card is an important financial decision. With so many cards offering cash back, rewards points, travel benefits, low introductory rates, and other features, it can be difficult to know which option is actually right for you.
A credit card that works well for one person may not be suitable for another. Your spending habits, payment routine, financial goals, and the fees you are willing to pay can all influence which card makes sense.
Before applying for a credit card, it is important to understand its main features and read the terms carefully. In this complete guide, FinanceTrack America explains the most important things you should know before choosing a credit card.
Know Why You Want a Credit Card
The first step is to understand your reason for getting a credit card.
Some people want a card for everyday purchases and cash back. Others are interested in travel rewards, building credit, managing expenses, or having a payment option for emergencies.
Your goal can help narrow down the available choices.
For example, if you rarely travel, a card designed primarily around airline or hotel rewards may not provide much value. If you frequently pay for everyday purchases, a cash-back card may be more useful.
Compare Credit Card Features
Credit cards can look similar at first, but their terms and benefits can be very different.
Before applying, compare important features rather than focusing only on advertisements.
| Feature | What to Check | Why It Matters |
|---|---|---|
| Annual Fee | Whether the card charges a yearly fee | Affects the total cost of keeping the card |
| APR | Standard purchase interest rate | Important if you carry a balance |
| Introductory APR | Length and terms of promotional rate | Can affect short-term borrowing costs |
| Credit Limit | Amount of credit available | Determines your available borrowing capacity |
| Rewards | Cash back, points, or miles | Can provide value on eligible spending |
| Welcome Offer | Requirements and expiration period | May provide additional rewards |
| Foreign Transaction Fee | Whether international fees apply | Important for travelers |
| Balance Transfer Fee | Cost of transferring another balance | Matters when consolidating debt |
| Cash Advance Fee | Cost of obtaining cash | Can make cash advances expensive |
| Late Payment Fee | Possible charge after a late payment | Helps you understand the cost of missed payments |
Look at the Annual Fee
An annual fee is a charge that some credit cards apply each year.
There are many cards with no annual fee, while others charge a yearly fee in exchange for additional rewards or benefits.
A card with an annual fee is not automatically a bad choice. The important question is whether the benefits you realistically expect to use are worth more than the fee.
For example, if a card has a yearly fee but provides rewards and benefits that you regularly use, it could potentially provide value. On the other hand, paying an annual fee for benefits you never use may not make financial sense.
Understand the Interest Rate and APR
APR is one of the most important details to check before applying for a credit card.
If you carry a balance, interest can increase the total amount you eventually pay. Credit cards can have different APRs depending on the type of transaction, including purchases, balance transfers, and cash advances.
Some cards advertise an introductory APR for a limited period. However, you should also check what APR may apply after the promotional period ends.
If you generally pay your statement balance in full, interest may be less important than it would be for someone who regularly carries a balance. Even so, understanding the APR is still important.
Consider Your Spending Habits
A credit card should fit your normal spending rather than encourage you to spend more.
Look at where you usually spend money. Your major categories might include groceries, gas, dining, online shopping, travel, entertainment, or recurring bills.
Some cards provide higher rewards in specific categories. Others offer a simple flat-rate reward structure.
Before choosing a rewards card, estimate how much you normally spend in the categories that qualify for higher rewards.
Understand Cash Back and Rewards
Rewards can be attractive, but it is important to understand the rules behind them.
Credit card rewards may include:
- Cash back
- Points
- Travel miles
- Statement credits
- Gift cards
- Travel-related benefits
Check how rewards are earned and whether there are limits or restrictions.
Also review how rewards can be redeemed. A card may advertise a high rewards rate, but its redemption rules could affect the actual value you receive.
The best rewards program is usually one that matches your existing spending habits.
Check the Welcome Bonus Requirements
Some credit cards offer a welcome bonus to new cardholders who meet specific spending requirements within a certain period.
For example, a card might require you to spend a particular amount during the first few months to receive a bonus.
Before applying, read the requirements carefully.
Do not make unnecessary purchases simply to qualify for a bonus. If meeting the spending requirement would cause you to spend more than you normally would or carry a balance, the bonus may not be worth the additional cost.
Check Foreign Transaction Fees
If you travel internationally or purchase products and services from businesses located in other countries, check whether the card charges foreign transaction fees.
Some credit cards do not charge these fees, while others may apply a percentage-based fee to eligible transactions.
This feature may not matter much if you only use your card domestically, but it can become important for frequent international travelers.
Understand the Credit Limit
Your credit limit is the amount of credit your issuer makes available under the terms of your account.
A higher credit limit does not necessarily mean a card is better. You should focus on whether the card’s overall features match your needs.
Also remember that your credit limit is not a spending target. Spending more simply because you have a larger limit can make it harder to manage your monthly payments.
Review the Fees Carefully
Credit cards can have several types of fees.
Depending on the card, these can include annual fees, balance transfer fees, cash advance fees, foreign transaction fees, late payment fees, and other charges.
Before applying, review the official fee information and card agreement.
Knowing these costs in advance can help you avoid unpleasant surprises later.
Consider the Payment Terms
Before choosing a card, understand how payments work.
Check the statement balance, minimum payment, payment due date, and other payment terms.
Paying on time is essential for responsible credit card management. If possible, many cardholders prefer to pay their statement balance in full to avoid carrying purchase balances and potentially paying interest, subject to the card’s terms.
Setting up payment reminders or automatic payments can help you stay organized.
Check the Card’s Benefits
Some credit cards offer additional benefits beyond rewards.
Depending on the card, benefits may include purchase protections, extended warranty features, travel-related protections, rental car benefits, or other services.
However, benefits can have conditions and limitations.
Do not assume that a benefit automatically applies to every purchase or situation. Read the terms to understand eligibility, exclusions, and coverage limits.
Compare Cards Before Applying
Avoid applying for the first credit card you see.
Create a simple comparison based on the features that matter most to you.
For example:
Card A: No annual fee, simple cash back, fewer travel benefits.
Card B: Annual fee, higher rewards potential, additional travel benefits.
Card C: Lower introductory APR, fewer rewards.
The right choice depends on your financial situation and how you expect to use the card.
Read the Fine Print
Credit card advertisements often highlight attractive features, but the complete terms contain much more information.
Before applying, review the card’s terms and conditions, including APRs, fees, promotional periods, rewards rules, eligibility requirements, and other important restrictions.
The fine print can explain details that are not obvious from an advertisement.
Avoid Choosing a Card Only for a High Reward Rate
A high reward rate may look attractive, but it should not be the only factor you consider.
Suppose a card offers excellent rewards but charges a large annual fee that you cannot justify through your normal spending. Another card may offer slightly fewer rewards but no annual fee.
The second option could potentially provide better overall value.
Always compare the complete package.
Final Thoughts
Choosing a credit card becomes easier when you know what to look for. Instead of focusing on one attractive feature, compare the complete cost and benefits of each card.
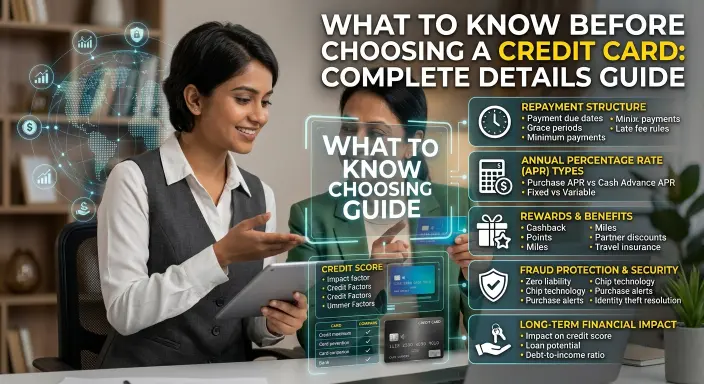
Pay attention to the annual fee, APR, credit limit, rewards, welcome offers, foreign transaction fees, balance transfer costs, cash advance fees, payment terms, and additional benefits.
Most importantly, choose a card based on your actual spending and financial habits. A credit card should be a useful financial tool, not a reason to spend beyond your ability to repay.
Before applying, always review the current terms and conditions provided by the card issuer because rates, fees, rewards, and offers can change.
FinanceTrack America provides educational information about credit cards, banking, and personal finance to help readers understand financial products and make more informed decisions.