 by
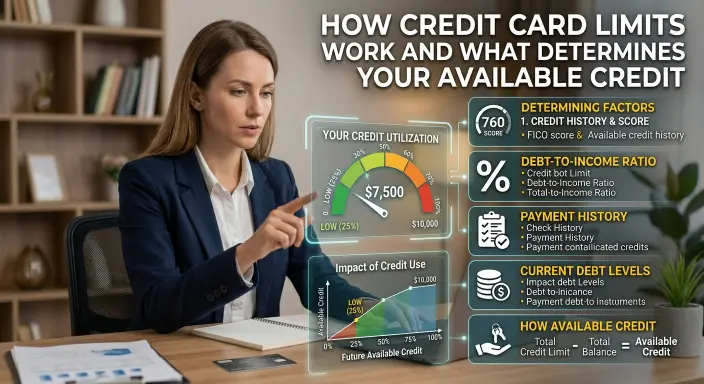
A credit card limit is one of the most important details to understand before using a credit card. It tells you how much credit your card issuer has made available to you. However, your credit limit is not necessarily the same as the amount you can spend at any particular moment.
Your available credit can change whenever you make purchases, receive credits, make payments, or have pending transactions. Understanding the difference between your credit limit and available credit can help you manage your account more effectively.
In this guide, FinanceTrack America explains how credit card limits work, what can affect your available credit, and what you should know before using a large portion of your credit line.
What Is a Credit Card Limit?
A credit card limit is the maximum amount of credit that a card issuer makes available to you under the terms of your account.
For example, suppose your credit card has a $5,000 credit limit. This means your account has a $5,000 credit line, subject to the card issuer’s terms and any applicable restrictions.
The limit is not free money. Any amount you borrow through purchases generally needs to be repaid according to your account terms.
Your credit card limit may also change over time. The issuer may increase or decrease the limit depending on its policies and information associated with your account.
What Is Available Credit?
Available credit is the amount of your credit line that remains available for new transactions.
For example, imagine your credit limit is $5,000 and you have $1,500 in posted purchases. Your available credit may be approximately $3,500.
However, the exact amount can vary because pending transactions, payments, credits, fees, and other account activity may affect the figure shown in your account.
This is why it is useful to check your credit card account before making a large purchase.
Credit Limit vs. Available Credit
These two terms are related but have different meanings.
| Credit Card Term | Meaning | Example |
|---|---|---|
| Credit Limit | Maximum credit available under the account | $5,000 |
| Current Balance | Amount currently owed according to account activity | $1,500 |
| Available Credit | Credit remaining for potential new transactions | About $3,500 |
| Pending Transaction | Transaction that has not fully posted | $200 |
| Payment | Money paid toward the account | $500 |
| Statement Balance | Balance shown on the latest billing statement | $1,200 |
| Minimum Payment | Smallest required payment under the account terms | Varies by issuer |
The numbers can change as transactions and payments are processed.
How Is a Credit Card Limit Determined?
There is no single number that determines your credit card limit.
Card issuers may consider multiple factors when deciding how much credit to offer. These can include information from your credit application, credit history, income information provided to the issuer, existing obligations, and the issuer’s own underwriting policies.
Different card issuers may evaluate applicants differently.
This means two people with similar financial profiles could potentially receive different credit limits from different issuers.
Credit History and Credit Scores
Your credit history can be an important part of a card issuer’s evaluation.
A credit report may contain information about previous and current credit accounts, payment history, balances, and other credit-related activity.
Credit scores are calculated using information in credit reports and can be one factor considered by lenders and card issuers.
However, a credit score does not automatically guarantee a particular credit limit. Each issuer has its own criteria.
Income Can Also Matter
When you apply for a credit card, the issuer may ask for information about your income.
Income can help an issuer evaluate your ability to manage potential credit obligations. The information you provide should be accurate and should follow the issuer’s application requirements.
Income is only one factor. It does not mean that someone with a higher income will automatically receive a higher credit limit.
Existing Debt and Financial Obligations
A card issuer may also consider your existing financial obligations when evaluating an application or account.
If you already have significant debt, the issuer may consider that information when determining the amount of credit it is comfortable extending.
The purpose of this type of evaluation is generally to assess the potential risk associated with extending additional credit.
Payment History Matters
Your payment history can play an important role in your overall credit profile.
Making payments on time can help maintain a positive payment history. On the other hand, missed or late payments can have negative consequences depending on the situation and the information reported to credit bureaus.
Responsible account management can therefore be important not only for avoiding fees but also for maintaining a healthy credit profile.
What Happens When You Use Your Credit Card?
Every time you make a purchase, the transaction generally reduces the amount of available credit once it is reflected in your account.
For example:
- Credit limit: $4,000
- Purchase: $600
- Remaining available credit: Approximately $3,400
If you later make a $600 payment and it is fully processed and credited to the account, your available credit may increase again.
However, the timing of payments and when credit becomes available can depend on the issuer’s policies.
Pending Transactions Can Affect Available Credit
Sometimes your available credit may be lower than expected even though you have not made many posted purchases.
One reason can be pending transactions.
A pending transaction is a transaction that has been authorized but has not yet fully posted to your account. Depending on the card issuer and merchant, pending amounts may temporarily reduce your available credit.
For example, hotels, rental car companies, restaurants, and other merchants may sometimes place authorization holds or temporary amounts on an account.
These amounts can change after the final transaction is processed.
Does Paying Your Credit Card Increase Available Credit?
Generally, when a payment is successfully processed and credited to your account, it can restore some of your available credit.
For example, if you have a $5,000 limit and your account balance is $2,000, a $1,000 payment could potentially increase your available credit by approximately $1,000 after the payment is processed.
However, the timing can vary by issuer, payment method, and account circumstances.
Never assume that a payment has immediately restored your available credit until your account confirms it.
Why Your Available Credit Can Change
Your available credit can change for several reasons.
Common factors include:
- New purchases
- Pending transactions
- Payments
- Refunds
- Credits
- Fees
- Interest charges
- Returned payments
- Adjustments made by the card issuer
Because of these factors, your available credit can change several times during a billing cycle.
Does a Higher Credit Limit Mean You Should Spend More?
No.
A higher credit limit simply gives you access to more available credit. It does not mean you should increase your spending.
For example, someone with a $10,000 credit limit does not need to spend $10,000 every month. Your spending should be based on your budget and ability to repay the balance.
A credit card can become difficult to manage when spending increases simply because more credit becomes available.
Credit Utilization and Your Credit Profile
Credit utilization generally refers to the amount of revolving credit you are using compared with your available credit limits.
For example, if you have a $10,000 credit limit and a $2,000 balance, the balance represents 20% of that limit.
Credit utilization is one factor that can be considered in some credit scoring models. However, different scoring models may evaluate credit information differently.
The important point is that using a large portion of your available credit can affect your credit profile, depending on the information reported and the scoring model being used.
Can a Credit Card Limit Increase?
Some issuers may increase a cardholder’s credit limit over time.
An issuer may review account activity and other available information when considering a credit line increase. Some issuers may also allow cardholders to request an increase.
A higher limit can provide additional flexibility, but it should not be viewed as permission to take on unnecessary debt.
Before requesting or accepting an increase, consider whether the additional credit fits your financial needs.
Can a Credit Limit Decrease?
Yes, a credit limit can potentially decrease depending on the card issuer’s policies and account circumstances.
A lower credit limit means less available credit. If your balance remains the same while your limit decreases, the percentage of your available credit being used can increase.
If you notice an unexpected change in your credit limit, review any communication from your card issuer or contact the issuer through an official channel.
How to Monitor Your Available Credit
Keeping track of available credit is simple when you regularly check your account.
You can usually view your credit limit, current balance, available credit, pending transactions, and recent payments through your card issuer’s official mobile app or online banking website.
Reviewing this information before making a large purchase can help you avoid exceeding your available credit.
It is also a good idea to review your monthly statement and check for transactions you do not recognize.
Final Thoughts
Understanding how credit card limits work can make managing a credit card much easier. Your credit limit represents the maximum credit available under your account terms, while your available credit represents the amount currently available for potential new transactions.
Your available credit can change because of purchases, pending transactions, payments, refunds, fees, and other account activity.
Credit card limits may be influenced by factors such as credit history, credit information, income, existing obligations, payment history, and the card issuer’s own policies.
Remember that a higher credit limit does not mean you should spend more. The most important goal is to use credit responsibly and keep your spending within an amount you can comfortably repay.
Before making financial decisions, always review the current terms provided by your card issuer because policies, limits, and account features can vary.
FinanceTrack America provides educational information about credit cards, banking, and personal finance to help readers better understand how financial products work.